
Homeowners Insurance in California: What a Standard Policy Really Covers
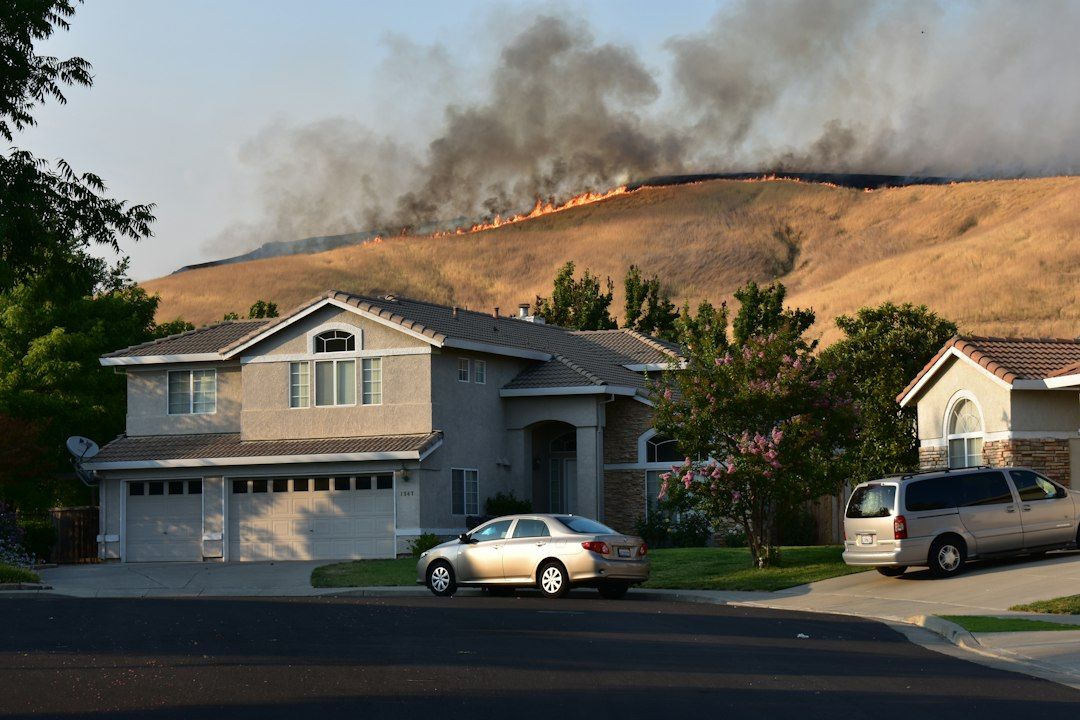
Owning a home in the Golden State is a dream for many, but protecting that investment has become increasingly complex. The devastating wildfires and severe winter storms of early 2025 proved that a house is more than just walls and a roof—it is your sanctuary and your most valuable financial asset.
Understanding Your Home's First Line of Defense
Owning a home in the Golden State is a dream for many, but protecting that investment has become increasingly complex. The devastating wildfires and severe winter storms of early 2025 proved that a house is more than just walls and a roof. It is your sanctuary and your most valuable financial asset. For over 15 years, our team at Sara Mirzaei Insurance Agency has guided families and business owners through the intricacies of property protection. In this article, we will break down exactly what a standard policy covers so you can make informed decisions about your financial future.
The Current Landscape of Homeowners Insurance in California
To truly understand your coverage, it helps to look at the broader environment. The state of california homeowners insurance market is undergoing a historic transformation. Following the catastrophic Palisades and Eaton fires in January 2025, which generated an estimated $33.9 billion in insured losses according to Bankrate, the industry faced unprecedented pressure. These events triggered rapid shifts in how companies evaluate risk and price their policies.
Currently, navigating the homeowners insurance california market requires adjusting to rising costs and changing regulations. The average premium for a standard policy sits around $1,641 annually, but residents in wildfire prone regions often see significantly higher rates. Inflation has also driven up the cost of construction materials and skilled labor, meaning the amount of money required to rebuild a damaged home is much higher today than it was just a few years ago.
In response to these market pressures, the California Department of Insurance has implemented the Sustainable Insurance Strategy. This regulatory shift, which gained full momentum moving into 2026, allows insurers to use forward looking catastrophe models rather than strictly historical data to price policies. The goal is to bring private insurers back into the market and stabilize options for consumers. However, during this transition, many homeowners have been forced onto the California FAIR Plan, which serves as the state insurer of last resort. The FAIR Plan saw a massive surge in enrollment in 2025, highlighting the critical need for expert guidance when securing private coverage.
When you are exploring your options, you must know what your policy actually promises to do. A basic understanding of your coverage prevents devastating surprises after a disaster. For a deeper look into statewide regulations, our California homeowners insurance guide offers extensive resources. Many clients come to us with existing policies from competitors, completely unaware that their dwelling limits have not kept pace with local inflation or that they lack adequate liability protection. Securing quality california home insurance is not just about fulfilling a mortgage requirement. It is about establishing a robust financial safety net that will stand up to worst case scenarios. At Sara Mirzaei Insurance Agency, we believe that education is the foundation of good coverage. By demystifying the terminology, we empower you to choose a customized plan that reflects your unique needs.
Core Coverages in a Standard California House Insurance Policy
When you review a typical california house insurance contract, you will find it is divided into several distinct categories. Each section is designed to protect a different aspect of your property and your financial wellbeing.
- Coverage A (Dwelling): This pays to repair or rebuild the physical structure of your home if it is damaged by a covered peril, such as fire, wind, or vandalism. The limit on this coverage should equal the total cost to rebuild your home from the ground up, which is often very different from its real estate market value. For example, if a severe winter storm causes a tree to crash through your roof, Coverage A handles the structural repairs.
- Coverage B (Other Structures): This extends protection to detached structures on your property. This includes detached garages, tool sheds, fences, and guest houses. Typically, this coverage is set at about ten percent of your overall dwelling limit.
- Coverage C (Personal Property): This protects your personal belongings. It includes furniture, electronics, clothing, and appliances. Whether your items are damaged by a kitchen fire or stolen during a break in, personal property coverage helps you replace them. It is highly recommended to opt for replacement cost coverage rather than actual cash value, as the latter factors in depreciation and will leave you with a much smaller payout.
- Coverage D (Loss of Use): This is vital during major disasters. If a covered event makes your home uninhabitable, this section pays for your additional living expenses. It covers hotel bills, restaurant meals, and storage fees while your home is being repaired. During the widespread evacuations of 2025, this coverage proved to be an absolute lifeline for thousands of displaced families.
- Coverage E (Personal Liability): If a guest slips on your wet patio and sues you for medical bills and lost wages, liability coverage helps pay for your legal defense and any resulting judgments. This is a crucial component of any home owner insurance california policy, as medical costs and legal fees can easily bankrupt an uninsured family.
- Coverage F (Medical Payments): This related component pays for minor medical bills for guests injured on your property, regardless of who is at fault, helping to prevent small accidents from turning into major lawsuits.
Expert Insights on Protecting Your Property
As an agency owner writing Farmers Insurance policies for over a decade and a half, I have witnessed firsthand the confusion that often surrounds property coverage. When shopping for house insurance california residents face unique regional risks. One of the most common misconceptions I encounter is the assumption that a standard policy covers absolutely everything. In reality, typical policies explicitly exclude damage from floods and earth movement. If you live near a fault line, exploring California earthquake insurance essentials is a necessary step to ensure complete protection.
Another critical insight for 2026 is the growing importance of home hardening. With the introduction of legislative efforts aimed at rewarding wildfire mitigation, insurance companies are heavily incentivizing property owners who take proactive safety measures. Upgrading to a fire resistant roof, installing ember resistant vents, and clearing defensible space around your property can significantly lower your risk profile. These steps not only keep your family safe but also make your property much more attractive to private insurers.
Furthermore, we frequently advise our clients to carefully document their belongings. Creating a home inventory video on your smartphone takes just a few minutes, yet it saves hours of stress if you ever need to file a personal property claim. Storing this video in the cloud ensures it survives even if your home is completely destroyed.
Many individuals and small businesses come to us after experiencing poor communication or rigid underwriting from their previous carriers. Our personalized approach means we sit down with you to identify specific gaps in your existing coverage. For instance, if you have high value items like jewelry or fine art, standard limits might not be enough, and you will need a specialized rider. We also recommend exploring home and auto insurance bundles in California as a highly effective strategy to secure premium discounts while keeping all your protection under one roof.
Ultimately, navigating the complexities of the current market does not have to be an overwhelming experience. Working with an experienced local agent ensures you are not just a policy number. We advocate for you, explain the fine print, and tailor a personal insurance plan that adapts to your evolving lifestyle.
Securing Your Future with the Right Protection
Understanding the mechanics of your property coverage is the most effective way to safeguard your financial future. As we have explored, a standard policy does much more than rebuild your walls. It replaces your treasured belongings, provides a temporary roof over your head during a crisis, and defends you against financially devastating liability lawsuits.
The insurance landscape in our state is constantly evolving, driven by changing weather patterns and updated regulations. Relying on an outdated policy can leave you exposed to significant out of pocket costs. Taking the time to review your coverage limits, understand your deductibles, and explore mitigation discounts will yield peace of mind that money simply cannot buy. Do not wait for the next major storm or wildfire season to discover what your policy lacks. Take proactive steps today to build a resilient safety net for the people and possessions you cherish most.
Sara Mirzaei Insurance Agency
Ready to ensure you have the right protection at the best possible rate? Contact us today for a comprehensive coverage review and a personalized quote tailored to your lifestyle. At Sara Mirzaei Insurance Agency, we pride ourselves on delivering a highly customized approach to your security. Whether you are buying your first home or looking to improve the policy you currently hold, our dedicated team is here to listen to your needs and provide dependable, cost effective solutions. Experience the peace of mind that comes from working with local professionals who truly care about your satisfaction. Reach out through our contact page or call our office to secure the expert guidance your family deserves.
By Sara Mirzaei & Team